BILL AP & AR Business Payments

- 1.54K Reviews
- 4.3
- Downloads
- 500,000+
Our take on BILL AP & AR Business Payments from Appgk
If you run a small business, keeping bills moving and incoming payments organized can become a daily distraction. BILL AP & AR Business Payments is built for that narrow but important job: helping businesses pay bills and get paid online from a mobile device. I found it most useful when I treated it as a companion to a business payment workflow rather than as a complete accounting system.
The app comes from Bill.com Inc. and sits in the business category. It is free to install, available for Everyone, and has passed the half-million-install mark. Its current release is version 3.7.171, and it supports devices running iOS 9 or later. Those details make it approachable for a broad range of users, especially someone who wants to check payment activity away from a desk without immediately committing to a paid mobile tool.
Getting from installation to a useful first payment task
My first impression is that this is an app for people who already have a business payment process in mind. The short store label, “BILL AP & AR,” is accurate but not especially explanatory for a newcomer. AP refers to accounts payable, the money your business owes, while AR refers to accounts receivable, the money others owe your business. Understanding that split before opening the app makes the screens much easier to interpret.
I would not approach it like a personal wallet or a simple bill-reminder app. The useful question is not “Can this remind me to pay something?” but “Can this help me handle business bills and incoming payments in one place?” That distinction matters because a freelancer, office manager, or business owner may use the same app for very different reasons.
Best Parts of BILL AP & AR Business Payments
Things to Keep in Mind About BILL AP & AR Business Payments
The best first-time goal is one small, clearly understood payment task. Instead of trying to organize every supplier and customer immediately, start by identifying one bill that is already approved and ready to move through your normal process. A focused first action makes it easier to understand where information belongs and whether the app fits the way your business works.
What the app is good at for a first-time user
The strongest appeal is convenience between office moments. A business owner may receive a bill while traveling, need to check whether a payment has progressed, or want to respond to an incoming-payment question without opening a laptop. A mobile business-payment app is valuable in those gaps, provided the underlying records are already clear.
News and Features Related to BILL AP & AR Business Payments

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I also like the separation between paying and getting paid. These are related tasks, but they create different kinds of work. Paying a supplier usually involves checking the bill, confirming the recipient, and deciding when money should leave. Getting paid involves tracking what a customer owes and keeping the incoming side visible. Keeping both areas available can reduce the temptation to manage one side in a spreadsheet and the other in email.
Still, I would not confuse access with automation. The app can make a payment workflow more reachable, but it cannot decide whether a bill is legitimate, whether the amount is correct, or whether a customer dispute has been resolved. Those decisions remain yours. The more carefully you prepare the information before using the app, the smoother the experience becomes.
Don't want to read the full review?
Setting up without creating avoidable confusion
Before starting, I recommend having the business details and payment information you normally use close at hand. You should also know which bills are ready for action and which ones are still waiting for approval. Mixing those two groups is one of the easiest ways to create uncertainty during setup.
Think of the first session as building a clean starting point, not importing your entire financial history. If you are responsible for payments but not for approving purchases, decide how you will distinguish an item that is ready from one that needs someone else’s review. That simple habit is more useful than rushing through a long list of old transactions.
Screenshots
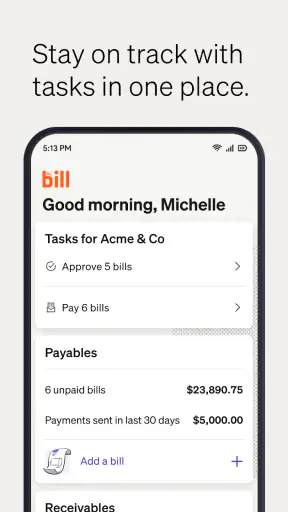
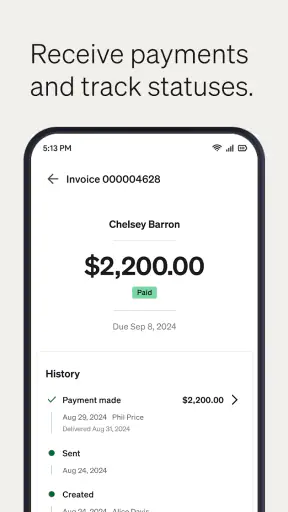
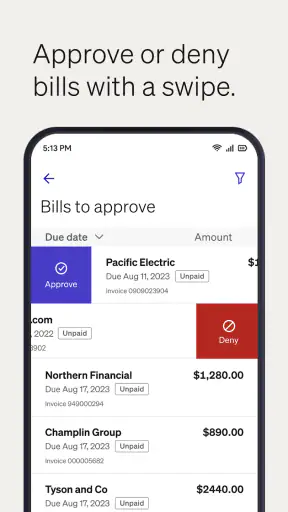
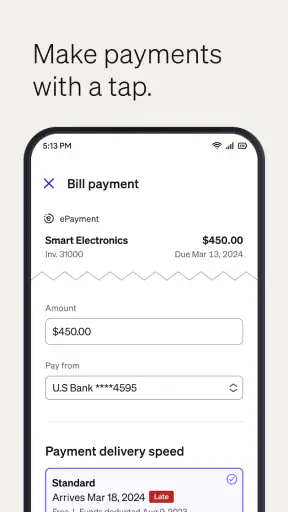
The app’s business focus also means that the right setup depends on your role. A sole proprietor may be able to keep the process simple and direct. An office administrator may need to coordinate with an owner or finance colleague before acting. Someone who only wants to split household expenses is likely looking in the wrong place; this is designed around business payments, not casual personal money management.
Your first meaningful action
For a practical first test, I would begin with an ordinary supplier bill that has a clear amount, a known recipient, and an agreed payment timing. Review the details before confirming anything, then use the app to move that bill through the payment process. The point is not merely to tap a button. The point is to see whether the app gives you enough confidence and visibility to know what happened afterward.
That follow-through is where a business tool proves its value. After taking action, return to the payment area and check how the item is represented. Can you tell whether it is still awaiting action, already progressing, or finished? If the status is easy to understand, the app is doing something useful beyond replacing a paper check or a desktop visit.
A realistic example would be a small design studio that receives a contractor invoice while the owner is away from the office. The owner can review the prepared bill, confirm that the work was delivered, and handle the payment task from the phone instead of leaving it buried in an inbox. Later, the same person can use the incoming-payment side to keep an eye on what a client owes. The benefit is not flashy; it is fewer loose ends.
How to use the accounts-payable side carefully
Accounts payable work rewards deliberate checking. Before approving or sending a payment, compare the bill with the information you already trust: the supplier name, the expected amount, and the reason for the charge. A mobile screen encourages quick decisions, so I would avoid processing unfamiliar invoices while distracted or in a hurry.
One useful habit is to separate review from approval mentally, even if both happen in the same session. First ask whether the bill belongs to the business and matches the service received. Then ask whether it is ready to be paid now. This two-step check helps prevent the common mistake of treating every visible bill as an immediate payment instruction.
Another practical tip is to use the app for exceptions as well as routine payments. If a supplier asks about a bill, checking its current position from the mobile app can be faster than searching through multiple messages. That does not replace a proper conversation about a disputed amount, but it can quickly tell you whether the item is waiting, moving, or already handled.
How the accounts-receivable side changes the workflow
Getting paid requires a different mindset. A customer’s unpaid balance is not automatically a late payment, and an incoming-payment record does not explain every reason money has not arrived. I found it helpful to use the AR side as a visibility tool: it shows which customer-related items deserve attention, while the actual follow-up still requires judgment.
For a consultant, this could mean checking whether a client payment is moving before sending a reminder. For a growing shop, it could mean reviewing incoming activity before deciding which outgoing bills can comfortably be handled. That connection between money coming in and money going out is one of the more useful reasons to keep both sides in the same business app.
The trade-off is that users who only need a basic invoice maker may find the broader payment workflow unnecessary. If your main need is creating attractive invoices and tracking time, a dedicated invoicing application may be a better match. This app makes more sense when payment movement itself is the problem you are trying to manage.
Common points of friction and misunderstanding
The biggest source of confusion for newcomers is terminology. AP and AR are familiar to finance professionals, but not everyone who handles business money uses those labels every day. Remembering “AP is money going out” and “AR is money coming in” gives you a simple map when moving between sections.
Another possible misunderstanding is expecting the mobile app to remove the need for business controls. A phone makes access easier, but easier access also makes it important to protect your review habits. Do not approve a payment solely because the item looks familiar at a glance. Take the extra moment to verify the details, particularly when the amount or recipient is unusual.
Users may also wonder whether this replaces accounting software. In my view, it should usually be considered a payment-focused part of a wider financial routine, not an automatic substitute for bookkeeping, reporting, or tax preparation. If you need detailed accounting analysis, reconciliations, or extensive reporting, a full accounting platform will generally be the stronger primary tool. The app is more appealing when the immediate pain is paying bills and tracking money owed.
There is also a difference between a free download and a completely cost-free business operation. The app itself is listed as free, but payment services and business workflows can have their own terms outside the simple act of installing an app. I would read the relevant details before making it central to a company’s financial process, especially if payment volume is high or several people will rely on it.
Small workflow improvements that make a difference
My first recommendation is to begin with current, uncomplicated items rather than old records. A clean, recent bill gives you a better test of the app’s usefulness than a backlog containing duplicates, partial payments, and disputed charges. Once you understand the flow, you can decide how much historical information is worth bringing into your routine.
Second, create a personal checkpoint before every important action. I would verify the recipient, amount, and timing in that order. This takes only a moment, but it turns a fast mobile interaction into a controlled business decision. It is especially helpful when you manage several suppliers with similar names.
Third, use the AR view when planning, not only when chasing overdue money. If expected customer payments are visible, they can inform conversations about upcoming expenses and cash timing. It does not guarantee that a customer will pay on schedule, but it gives you a more grounded picture than relying on memory.
Fourth, treat status information as a prompt for follow-up rather than as a final answer. If a payment appears stalled, investigate the reason through your normal business contacts and records. The app can help you notice that something needs attention; it cannot resolve a supplier mismatch or a customer disagreement by itself.
Who should use it and who should choose something else
I would recommend BILL AP & AR Business Payments to a small-business owner, freelancer with recurring business bills, or office worker who needs mobile access to outgoing and incoming payment activity. It is particularly sensible for someone who loses time switching between email, spreadsheets, and a desktop payment portal.
I would be more cautious if you are looking for a personal finance app, a household bill calendar, or a full bookkeeping replacement. Those needs call for different priorities. A personal finance tool usually emphasizes budgets and spending categories, while accounting software focuses on records and reports. This app’s value is narrower and more operational: helping business payments move through a dedicated workflow.
Teams should also think about responsibility before adopting it. If one person pays bills, the decision is straightforward. If several people share finance duties, agree on who reviews, who approves, and who follows up before relying on the app. A mobile tool cannot compensate for an unclear internal process.
What the reception and age rating suggest
The app holds a 4.3 average from around 7.5 thousand ratings, with roughly 1.5 thousand written reviews. That is a useful sign that it has been tried by a substantial group, although a rating cannot tell me whether every business workflow will match my own. Payment tools are especially sensitive to company habits, approval rules, and the type of bills being handled.
Its Everyone content rating is reassuring from an accessibility perspective, but it should not be read as a statement that every business user will find the workflow simple. Financial responsibility still requires care, even when the app is suitable for a broad age range.
My recommendation after using the workflow
I see this as a practical mobile doorway into business payments, not a magic solution for financial administration. Its strongest use is the moment when a legitimate bill is ready, a customer payment needs checking, or a business owner needs visibility away from a computer. The combination of AP and AR gives it more purpose than a basic bill reminder, especially for people who manage both sides of cash movement.
The app is worth trying because the download is free and the first test can be small. Start with one known bill, check the result, then look at how incoming payments fit into the same routine. If you finish that exercise with a clearer view of what needs action, it has earned a place in your workflow.
My final advice is to keep expectations precise. Use it to make business payment tasks more reachable and easier to monitor, while keeping your usual checks for accuracy, approval, and recordkeeping. For that focused job, BILL AP & AR Business Payments is a sensible option. It is less convincing for anyone who wants a complete accounting suite or a personal money manager, but for a first-time business user seeking a clearer path from bill to payment, it offers a reassuring place to begin.
BILL AP & AR Business Payments FAQ
What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. After reviewing its workflow, the main functions include paying vendor bills, sending invoices, collecting customer payments, organizing approvals, and tracking payment activity. It is aimed primarily at businesses rather than personal budgeting users.
Can BILL AP & AR Business Payments automate bill payments and invoice collection?
Yes, automation is one of the platform’s main advantages. Businesses can organize recurring bills, schedule payments, create approval workflows, and send invoices or payment requests to customers. Depending on the selected plan, payment method, and account configuration, some features may have processing times, transaction fees, or eligibility requirements. Users should review the current pricing and payment terms before enabling automatic transactions.
Is BILL AP & AR Business Payments secure for business transactions?
BILL AP & AR Business Payments includes security and account-control features intended for handling business financial activity, such as user permissions, approval processes, account verification, and transaction monitoring. However, no online service eliminates every risk. Before using it, companies should enable strong passwords and multi-factor authentication where available, limit employee permissions, verify payment details independently, and regularly review account activity for suspicious changes.
Does the app support integrations with accounting software and business tools?
The platform is designed to work with common business accounting and financial workflows, and integration support may be available for accounting software, banks, and other productivity tools. The exact integrations can depend on the subscription, region, and software version. In practice, users should confirm compatibility before downloading or migrating data, especially if they need synchronized invoices, vendor records, payment statuses, or reconciliation information.
Are there fees or limitations when using BILL AP & AR Business Payments?
BILL AP & AR Business Payments may include subscription costs, transaction fees, expedited payment charges, foreign exchange costs, or other pricing differences depending on the payment type and plan. Certain features can also require verification or may not be available in every country. Before signing up, businesses should examine the latest pricing page and terms carefully, particularly if they expect high payment volume or international transactions.